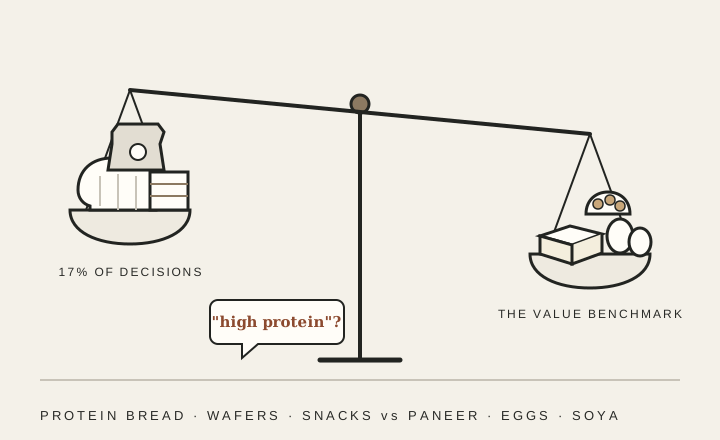
Of protein decisions concern bread, cookies or snacks
Half concern powders, dairy and bars
81%
Of buyer opinions on the protein claim are negative
Vs 31% on protein quality
36%
Of stated needs on these formats are about protein
Vs 83% for whole foods
74%
Of buyer opinions on price premiums are negative
₹0.85/g
Protein bread, in buyers' own maths
Vs ₹2.78/g for a 100 g paneer pack
Evidence basis: what buyers say they did and why, in their own words. External data is cited in the report.
In buyers' words
What buyers are saying
“
Not all “protein breads” are actually giving you protein… some are just regular bread with better marketing
On protein breads“
They're calling 4gm protein in 35 gms as high protein. That's not even 12%.
A buyer doing the maths on a snack“
120 ke chips? Bruh india me 90 ka shawarma aata hai with good amount of chicken and its fulfilling.
₹120 for chips? In India you get a ₹90 shawarma with a good amount of chicken, and it's filling.
Protein chips priced against a meal“
For me personally, protein wafers are a way to suppress my sugar cravings
Protein wafers as a better snack
01
Executive synthesis
NBW Brain analysed what Indian buyers say they did with protein bread, protein cookies, biscuits and wafers, and protein savoury snacks: why they chose them, and what they compared them with. Five findings pass the evidence tests. The first two matter most for positioning. These formats are a small part of how buyers get their protein, and the biggest barrier is doubt about the claim on the pack, far more than about the protein itself.
How to read the numbers
Figures are shares of what buyers said and did; every exhibit in the full report states its base. They are shares of captured evidence, not of consumers, spend or the market. Recurring patterns are labelled by strength rather than counted. Buyer quotes are verbatim.
01
Buyers mostly meet their protein need outside bread, cookies and snacks.
17% of decision events that name a type of option concern protein bread, cookies or snacks. Half (50%) concern protein powders, protein dairy and bars, and 24% whole foods or home-made versions.
Evidence · Corpus metric. Among completed purchases, trials and routines the three formats are 18%. Supported.
02
People doubt the protein claim far more than the protein itself.
81% of buyer opinions on whether a protein claim is believable are negative, against 31% of opinions on protein quality itself.
Evidence · Corpus metric. 94% of the claim doubt arises outside discussions led by label-audit channels. Supported.
Free sample from the full report
The biggest barrier: belief in the claim on the pack
Exhibit 4
Belief in the claim versus opinion of the protein
Share of comments that are negative
Claim credibility
81% negative
Ingredient trust
56% negative
Brand trust
52% negative
Protein quality
31% negative
Positive Negative mixed or neutral
16 more sections in the full report
Continue beyond the preview
One purchase gets you the full report, the licensed PDF and chat with this Brain's data: ask your own questions and see the quotes and sources behind every answer. Three months of access. The final total is shown at checkout.
₹9,999Full price ₹14,999Save 33%
Launch offer ends 31 October 2026. Full price after that.
Ask the cohort
The segments that move this market
4 segments, each defined by what people want and measured by what they do against the whole market. Here are 2 of them; the full Brain opens every one and lets you ask them your own questions.
Segment
Protein-target chasers
They build a protein system, not a snack habit: they combine sources and cook with protein atta about twice as often as the market, and try new packaged products half as often.
1.9×Combine several protein sources more often than the market
1.9×Cook with protein atta and flours more often than the market
“i also eat 6 eggs a day that provides another 30g of protein”
Segment
Taste-first snackers
Impulse triers with a short fuse: they try twice as often as the market and research half as much, so the first bite decides everything.
2.1×Try new products more often than the market
0.6×Shortlist and research less often than the market
“anything with protein added tastes so bad man, id rather stay empty instead of snacking”
In the full BrainBetter-snack switchers
In the full BrainDeal and novelty triers
Open all 4 segments and ask them your own questions
What each segment does more, and less, than the rest of the market
Who counts in each one, so you can find them in your own data
Answers from that segment's evidence alone, with the quotes behind them
₹9,999Full price ₹14,999Save 33%
Launch offer ends 31 October 2026. Full price after that.
Also in this Brain, not yet open for questions: Label sceptics · Family feeders.